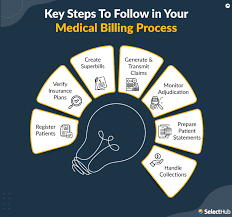
Picture this: you’re sneezing like a lawn sprinkler, your throat feels like sandpaper, and you finally drag yourself to the doctor. You’re thinking, “One quick visit, a prescription, and I’m back to binge-watching my favorite show.” But oh, dear reader, the journey from that exam room to your final medical bill is a wild ride through a bureaucratic funhouse. The medical billing process explained is like trying to unravel a mystery novel written by a committee of confused accountants. Don’t worry, though—I’m here to break it down with a sprinkle of humor and a lot of clarity. For a deeper dive into this chaotic world,
Why Is Medical Billing So Complicated?
Let’s start with the big question: why does a 15-minute doctor visit spawn a bill that looks like it was written in ancient hieroglyphs? The answer lies in the multi-step process that involves your doctor, their office staff, insurance companies, and sometimes a rogue fax machine that’s still stuck in 1995. Each step is a potential plot twist, and trust me, there’s no shortage of drama.
Medical billing isn’t just about charging you for a stethoscope session. It’s a carefully choreographed dance of codes, claims, and paperwork that ensures everyone gets paid—except maybe your sanity. This process is designed to balance the needs of healthcare providers, insurers, and patients, but it often feels like a game of telephone where the message gets garbled.
Step 1: The Doctor Visit—Where It All Begins
You walk into the doctor’s office, clutching your insurance card like it’s a golden ticket. The doctor listens to your complaints, maybe pokes you with a tongue depressor, and sends you on your way with a prescription for something unpronounceable. Easy, right? Wrong. Behind the scenes, the doctor is scribbling notes that will become the foundation of your bill. These notes include details about your symptoms, diagnosis, and treatment—basically, the medical equivalent of a grocery list.
But here’s the kicker: every sneeze, cough, or “I don’t know, it just hurts” gets translated into a specific code. These codes, known as CPT (Current Procedural Terminology) and ICD-10 (International Classification of Diseases), are the secret language of medical billing. One wrong code, and your sore throat visit could be billed as a rare tropical disease. No pressure, doc.
Coding: The Art of Turning Your Visit Into Numbers
Coding is where the magic—or mayhem—happens. A trained medical coder (think of them as the unsung heroes of the billing world) takes the doctor’s notes and assigns codes for every service provided. Did the doctor check your ears? That’s a code. Did they give you a flu shot? Another code. Did they spend five minutes explaining why you shouldn’t Google your symptoms? You guessed it—there’s a code for that too.
These codes are critical because they tell the insurance company exactly what happened during your visit. But they’re also a breeding ground for errors. A misplaced decimal point or a misread scribble can turn a routine checkup into a billing nightmare. And let’s be honest, doctors aren’t exactly known for their calligraphy skills.
Step 2: The Billing Office Takes Over
Once the codes are locked and loaded, the doctor’s billing office steps in. This is where your visit officially becomes a financial transaction. The billing team creates a claim, which is like a fancy invoice that gets sent to your insurance company. The claim includes all those precious codes, along with details like the date of service, the provider’s name, and how much the doctor thinks they deserve for dealing with your sniffles.
But here’s where it gets extra spicy: the billing office has to follow strict rules set by your insurance company. Miss a deadline or forget a form, and the claim could be rejected faster than a bad Tinder match. And if you thought dealing with insurance was fun, just wait until you hear about the next step.
Insurance: The Gatekeeper of Your Wallet
Your insurance company receives the claim and begins its own investigation. They’re like the Sherlock Holmes of medical bills, except instead of solving crimes, they’re deciding whether your doctor’s services were “medically necessary.” This is where things can get downright absurd. Did you need that extra X-ray? Was that second blood test overkill? The insurance company’s adjusters will scrutinize every detail, and they’re not afraid to say, “Nah, we’re not paying for that.”
If the claim is approved, the insurance company sends back an Explanation of Benefits (EOB), which is basically a report card for your doctor’s bill. The EOB tells you what’s covered, what’s not, and how much you owe out of pocket. Spoiler alert: it’s rarely zero. If the claim is denied, the billing office has to start the process all over again, which is about as fun as untangling Christmas lights.
Step 3: You Get the Bill (Cue the Dramatic Music)
After the insurance company has had its say, the doctor’s office sends you the final bill. This is the moment of truth, where you open the envelope (or email) and discover that your “quick visit” costs more than your monthly grocery budget. The bill includes your co-pay, deductible, and any services the insurance company refused to cover—like that time the doctor charged you for “therapeutic listening” when they were just nodding along to your complaints.
At this point, you might be tempted to call the billing office and demand answers. Good luck. Navigating the billing department is like trying to solve a Rubik’s Cube blindfolded. You’ll likely end up on hold, listening to elevator music, while you question every life choice that led you to this moment.
Surprise Bills: The Plot Twist Nobody Asked For
Just when you think you’re in the clear, you might get hit with a balance bill—a surprise charge for services you didn’t even know you received. Maybe the lab that tested your blood sample was out-of-network, or the anesthesiologist who popped in for 30 seconds during your procedure wasn’t covered by your insurance. These bills are the medical equivalent of finding out your coffee order comes with a $10 “ambiance fee.”
How to Survive the Medical Billing Maze
By now, you’re probably wondering how to avoid getting lost in this labyrinth of codes and claims. Fear not—I’ve got some tips to keep you sane:
- Check Your Insurance Coverage: Before you even step foot in the doctor’s office, make sure you understand what’s covered. Call your insurance company and ask about co-pays, deductibles, and out-of-network providers. It’s not the most thrilling conversation, but it’s better than a surprise $500 bill.
- Ask Questions: When you get a bill that looks like it was written in Klingon, call the billing office and ask for a breakdown. Be polite but firm—channel your inner Karen, but, like, a nice one.
- Keep Records: Save every EOB, bill, and receipt. You never know when you’ll need to prove that you already paid for that flu shot.
- Consider Professional Help: If the process feels overwhelming, companies like Help navigate the medical billing jungle. They’re like the Gandalf to your Frodo, guiding you through the chaos.
Conclusion
The medical billing process explained is a lot like a sitcom: it’s confusing, occasionally infuriating, but somehow you keep coming back for more. While it’s tempting to throw your bills in a drawer and hope they magically disappear, understanding the process can save you time, money, and a few gray hairs. So, the next time you visit the doctor, remember that you’re not just getting a checkup—you’re starring in your very own billing adventure. Grab some popcorn, keep your sense of humor.
Frequently Asked Questions
Why do medical bills take so long to arrive
Blame the back-and-forth between the doctor’s office and the insurance company. It’s like a slow-motion tennis match, except nobody’s keeping score.
Can I negotiate my medical bill?
Yes! Many providers are willing to work out payment plans or even reduce the bill if you ask. Just don’t expect them to throw in a free lollipop.
What happens if I ignore a medical bill?
Ignoring a bill is like ignoring a toddler throwing a tantrum—it only gets worse. Your bill could go to collections, which is bad news for your credit score.